Home Insurance Pensacola, FL: Costs and Coverage Guide in 2026
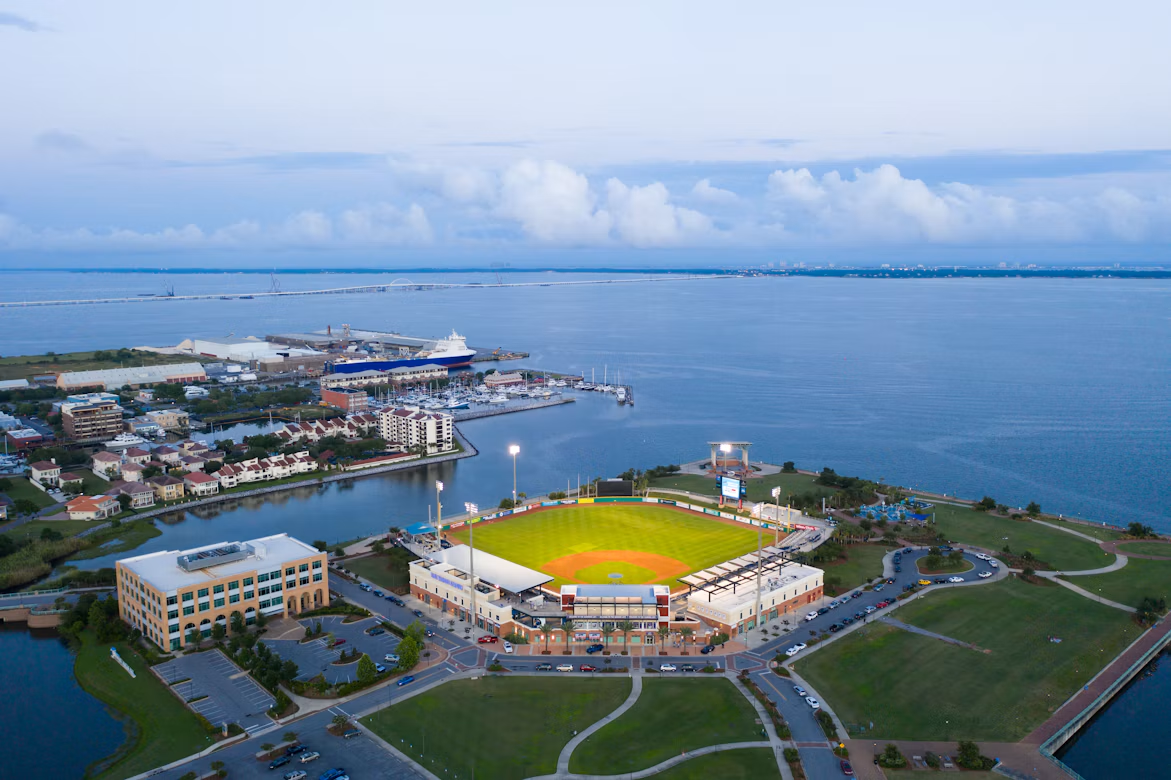
Home insurance in Pensacola, FL costs $3,702 a year on average for a policy with wind coverage, according to the county data. That puts Escambia County roughly 10% above the statewide average of about $3,355, not the Panhandle bargain many buyers expect. Also, coverage looks different for a mainland owner, a Pensacola Beach leaseholder, and a military buyer, and rates swing sharply between the mainland and the beach.
With that said, in this guide, we cover costs by area, beach lease rules, Navy relocation steps, hurricane coverage, and carriers to compare.
Key Takeaways
- Escambia County homeowners pay about $3,702 a year on average, above the $3,355 statewide figure.
- Pensacola Beach homes sit on leased land, often in FEMA flood zones, so lease review and flood coverage matter.
- Navy buyers should line up quotes before making an offer and confirm USAA eligibility early.
- Standard policies cover hurricane wind damage but not flood, and a separate hurricane deductible applies.
- Cheapest and best are different questions, so compare coverage, deductibles, and carrier strength side by side.
How Much Is Home Insurance in Pensacola, Florida?
Home insurance in Pensacola, FL costs about $3,702 a year on average for a policy with wind coverage, based on insurance rates by county in Florida.
Compared with other cities in Florida, Pensacola lands above Tampa, Orlando, and Fort Myers. Among these markets, only Fort Lauderdale (Broward County) sits far higher. Gulf exposure, rebuilding costs, and hurricane history all feed into Pensacola home insurance rates. Older roofs and low deductibles raise individual quotes, while newer roofs and wind mitigation features lower them.
The table below lines up Escambia County against other major markets and the statewide average:
Citizens Property Insurance, the state-backed insurer of last resort, offers a second reference point. According to their August 2026 report by county, there are 885 personal multiperil policies in Escambia County. Dividing premium by policy count gives about $2,467 a year for those policies and about $3,394 for the 1,766 wind-only policies.
However, Citizens sets its own rates, so those averages are not private-market quotes, and its statewide policy count has fallen to 266,231 as private carriers took on more homes. Therefore, treat any average home insurance cost as a starting range, because coverage and pricing vary by carrier, property, and eligibility.
Mainland vs. Pensacola Beach
Mainland and Pensacola Beach have different prices, and while the county average blends them together, there are several factors that influence the actual cost.
The table below groups Pensacola home insurance rates into four common zones and shows how exposure, carrier choice, and underwriting concerns change:
Barrier-island properties face the highest exposure, a pattern similar to Clearwater. Older and historic homes bring a different challenge. Carriers often request four-point inspections of the roof, electrical, plumbing, and HVAC systems, and rebuilding period details can cost more than market value suggests. Two homes a few blocks apart can also sit in different flood zones, so quote the exact address, not the neighborhood.
Pensacola Beach: Leasehold, Flood, and Rental Rules
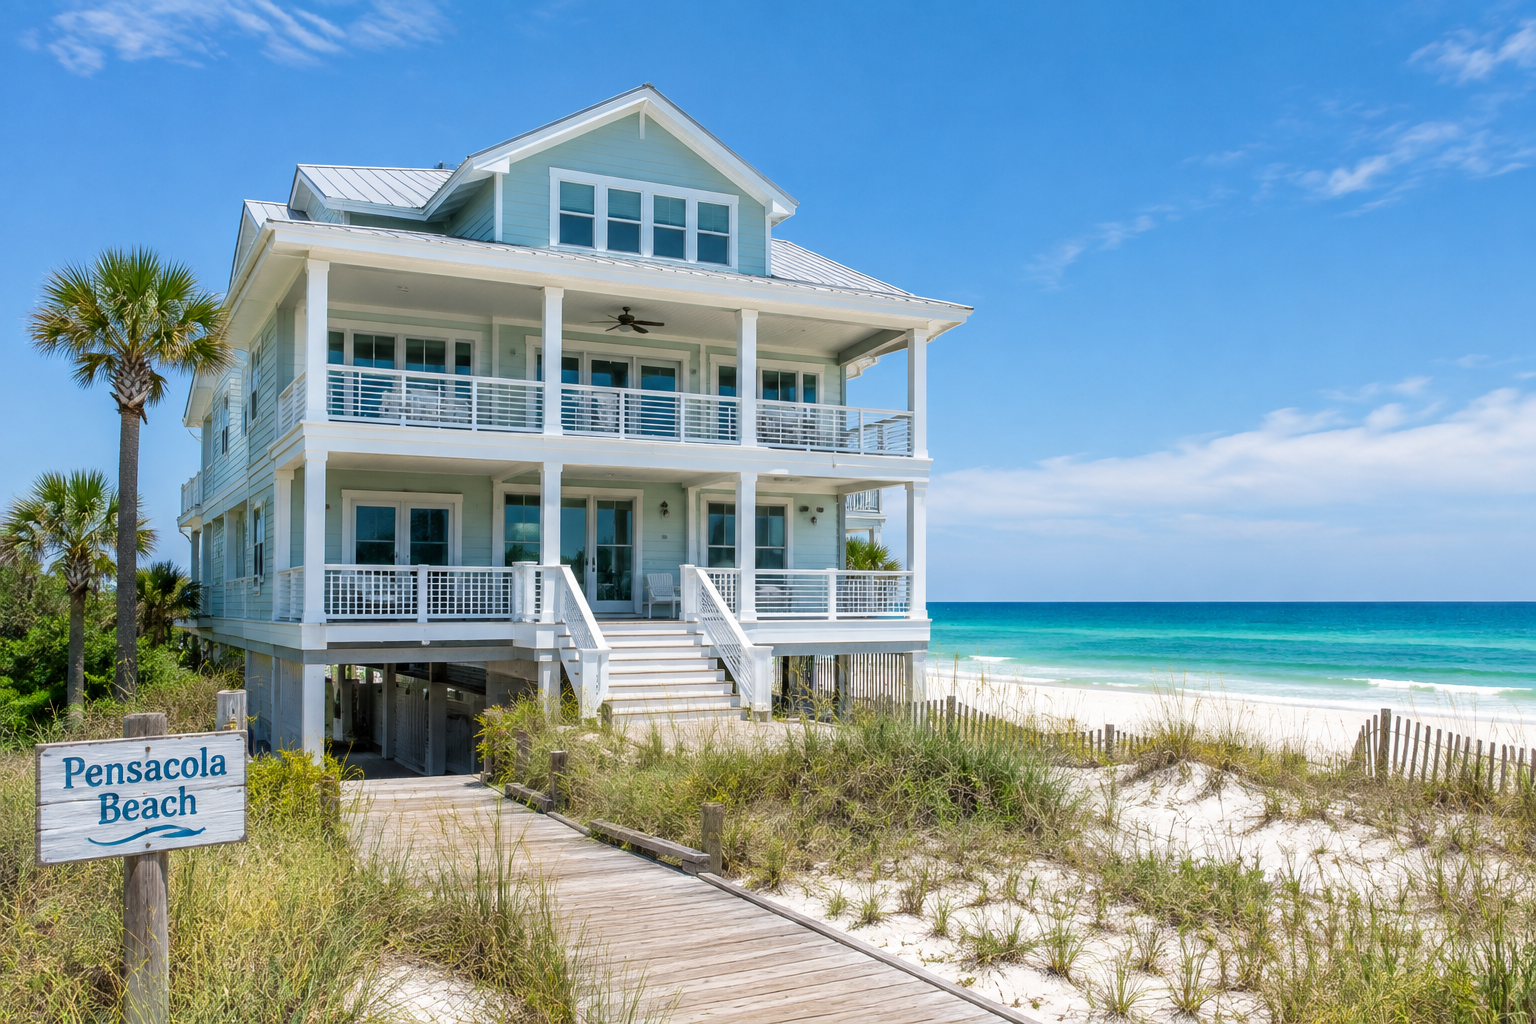
Pensacola Beach is leasehold land, not fee-simple property. Escambia County owns the land and the Santa Rosa Island Authority administers it, so beach homeowners own the building and lease the lot beneath it. Three rules shape coverage:
- Leasehold terms. Review the lease for insurance and indemnity clauses before you buy. Lenders, including FHA and VA lenders, often set specific flood and master-policy requirements, so confirm them early. Ask the Santa Rosa Island Authority whether renovations need approval before work starts, because unpermitted changes can complicate coverage.
- Flood zones. Many parcels sit in FEMA V or AE flood zones, which makes flood coverage essential. Check your parcel on FEMA's Flood Map Service Center, and price a flood insurance policy next to your home policy. An elevation certificate may help refine flood pricing. Condo owners on the beach or Perdido Key should also review condo insurance.
- Rental use. Owners who rent short-term generally need a license from the Florida Department of Business and Professional Regulation and a county vacation rental license. A standard homeowners policy typically excludes rental use, so vacation homeowners often need a different policy type. Second-home owners who leave a property empty for stretches should also ask about vacancy limits, and ask each carrier how it treats short-term guests.
Moving to Pensacola for the Navy: 4 Key Insurance Steps
If you’re a Navy buyer moving to Pensacola, you need insurance quotes lined up before you make an offer. Orders arrive on a tight clock, and insurance should fit inside it:
- Receive orders and set a target closing date.
- Start the house hunt and request quotes before you make an offer, since roof age and flood zone change the monthly payment.
- Check USAA eligibility first, because it depends on service status and family ties.
- Bind coverage before closing. VA lenders require hazard insurance, and flood coverage when the home sits in a flood zone.
Lenders want proof of coverage at closing, so have the binder ready before the final walkthrough. Ask the agent which flood zone the home sits in, since Naval Air Station Pensacola neighborhoods range from inland streets to low-lying waterfront blocks. If a later move leaves you owning a home you can't occupy, tell your carrier early, because vacancy rules can limit coverage.
Deployment changes the picture. A vacant or rented home needs a different policy than an owner-occupied one, so review landlord insurance if you rent the house out. Service members renting their own housing can look at renters insurance. Ask each carrier how long a home can sit unoccupied during a deployment before coverage changes, because limits vary and a short gap can matter.
Does Pensacola Home Insurance Cover Hurricane Damage?
Pensacola home insurance typically covers hurricane wind damage, but it does not cover flood or storm surge. A standard Florida homeowners policy includes windstorm coverage subject to a separate hurricane deductible, while rising water requires a separate flood policy.
Typically covered:
- Wind damage to the roof and structure
- Damage from falling trees
- Additional living expenses while repairs continue
Typically excluded:
- Flood
- Storm surge
- Rising water
Hurricane Sally in September 2020 showed why the split matters. The Category 2 storm made landfall near Orange Beach, Alabama, then crawled inland and dropped 24.8 inches of rain on downtown Pensacola, with 6–7 feet of surge along the coast. Wind drove most insured losses, yet owners without separate flood coverage faced water damage on their own. Many Pensacola owners also learned that roof age and prior mitigation work shaped how smoothly claims moved, so keep photos and receipts of upgrades.
Florida insurers must offer hurricane deductibles of $500, 2%, 5%, and 10% of dwelling coverage. The deductible takes effect when a hurricane warning covers any part of Florida, lasts until 72 hours after it ends, and typically applies once per season rather than once per storm.
Carriers typically pause new policies and coverage changes when a storm threatens, so review your policy before one forms.
Best Home Insurance Companies in Pensacola
The best home insurance in Pensacola isn’t about the cheapest choice. A low insurance premium can hide a high hurricane deductible or thin coverage, while a higher premium may buy stronger limits.
Also, check financial strength before you compare prices. Rating agencies such as AM Best and Demotech grade an insurer's ability to pay claims, and a strong rating matters most after a major storm, when many claims arrive at once.
Carriers that appear in Pensacola today include Florida Peninsula, American Integrity, Security First, Kin, Slide, and Chubb for higher-value homes. Citizens Property Insurance Corporation is the state-backed option when private carriers decline a property.
Once you know who writes policies in Pensacola, the next step is the premium itself. Five steps can lower the premium without gutting coverage:
- Order a wind mitigation inspection to document roof shape, shutters, and roof-to-wall connections.
- Choose a higher hurricane deductible only if you could pay it in cash.
- Replace or document an aging roof.
- Bundle your policy with car insurance.
- Shop again at every renewal.
How to Compare Home Insurance Quotes in Pensacola
You can compare home insurance quotes Pensacola carriers offer by matching dwelling limits, deductibles, and exclusions across at least three carriers. Ask for the same coverage in writing, then compare the full yearly cost: the premium, the hurricane deductible, and any flood policy.
Worth Insurance handles that comparison for you. As an independent home insurance agency in Florida, we compare quotes from multiple carriers instead of selling one company's policies, so you see coverage and pricing side by side. Licensed agents review your roof, flood zone, and coverage needs before presenting options, and you decide which policy fits.
When you're ready, get a free quote from Worth Insurance and see how carriers stack up for your address.
Final Thoughts
Pensacola home insurance rates sit above the Florida average, but your real number depends on where the home sits, how old the roof is, and which deductible you choose. Mainland owners, Pensacola Beach leaseholders, and military buyers each face different rules, and flood coverage matters for all three. Compare several quotes before you commit, and review your coverage every year as roof age and rebuilding costs change.
Home Insurance Pensacola, FL FAQs
#1. What is the average cost of homeowners insurance in Pensacola, Florida?
The average cost of homeowners insurance in Pensacola, Florida is about $3,702 a year for a policy with wind coverage, based on OIR's data for Escambia County. Your premium depends on roof age, dwelling coverage, deductible, and distance from the water, so beach and bayfront homes usually price well above inland ones.
#2. Do I need flood insurance in Pensacola?
You need flood insurance in Pensacola if your home sits in a FEMA high-risk zone and carries a federally backed mortgage. Many homeowners outside those zones choose it too, because standard policies exclude flood and water damage in areas the maps don't flag. A separate flood policy usually has a waiting period, so ask about timing before storm season.
#3. Is USAA for military members only?
USAA is not open to the general public, but eligibility extends beyond active-duty members. Veterans and some family members, such as spouses and children of members, may also qualify. Confirm eligibility directly with USAA before you rely on a quote, and compare it against other carriers.
#4. Is mobile home insurance different from regular homeowners insurance?
Mobile home insurance is different from regular homeowners insurance because carriers use separate policy forms and weigh the home's age, tie-downs, and construction type. Mobile home insurance in Pensacola, FL typically goes through specialized carriers, so confirm wind, flood, and replacement cost terms for manufactured home insurance in Pensacola.
#5. Do veterans get a discount on homeowners insurance?
Veterans do not receive a universal discount on homeowners insurance, though some carriers offer military or veteran credits. A VA loan itself doesn't lower premiums. Ask each carrier about affinity discounts, such as military or veteran credits, then compare the discounted quote against the others.

Get a
Florida Home Insurance
Quote
To see how Worth can reduce your risk.
Get a Free Quote


