Fort Myers Home Insurance: 2026 Costs, Coverage and Hurricane Rules
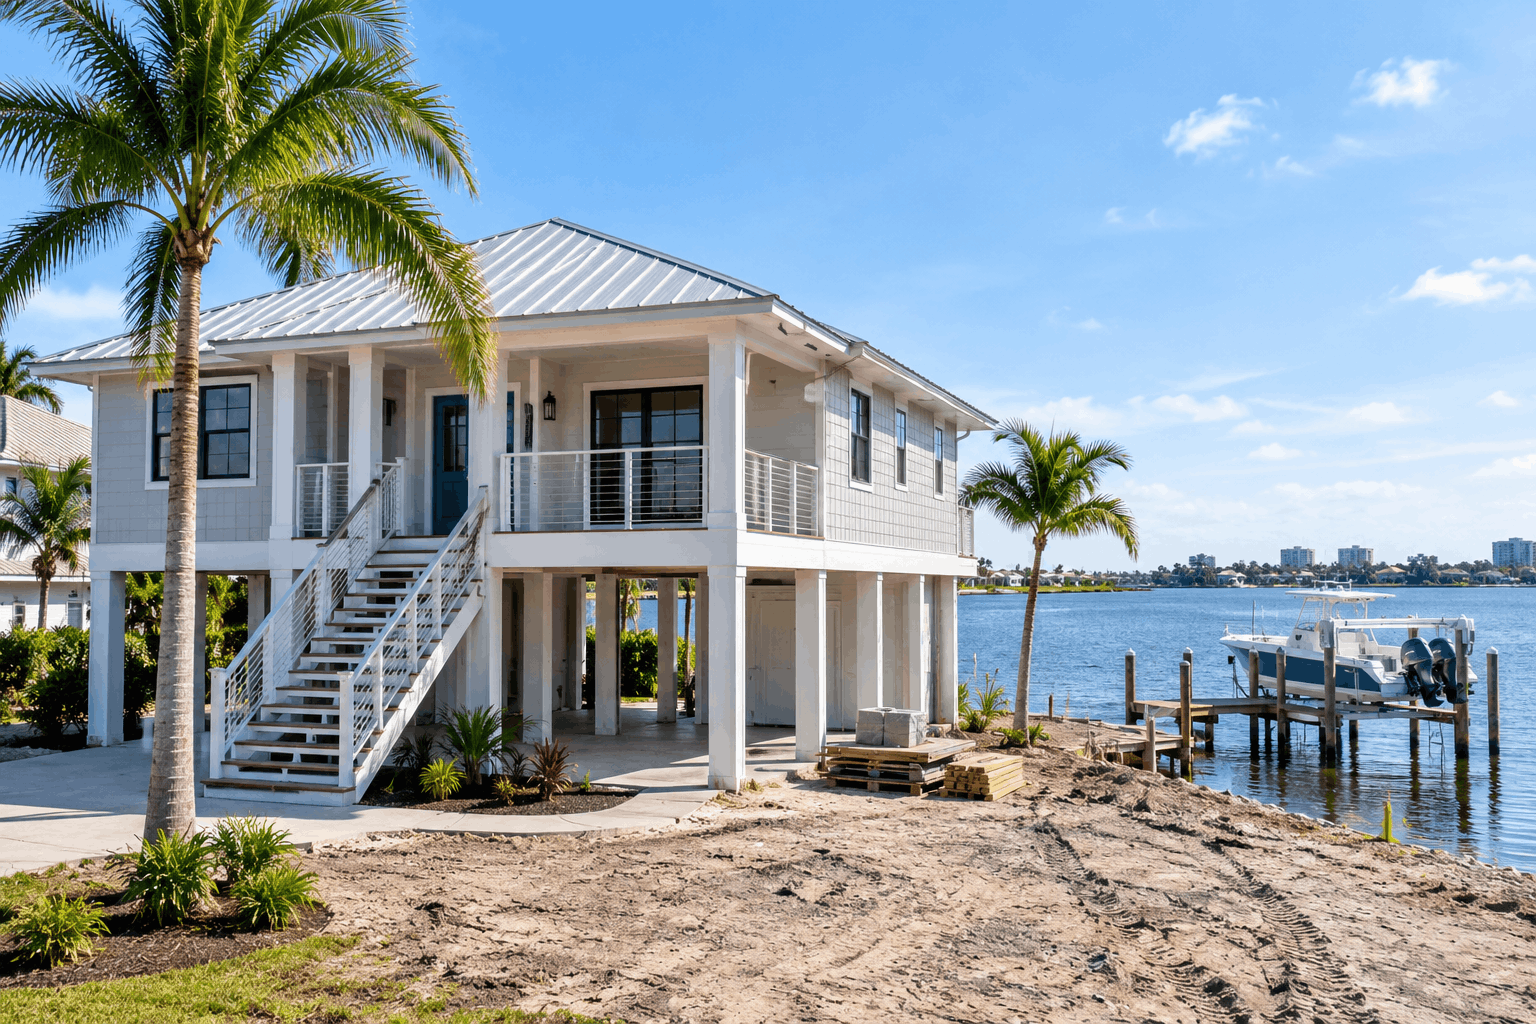
Fort Myers home insurance is still available, but it is more selective than before Hurricane Ian. Lee County took the worst of Hurricane Ian in 2022, and the market is still shaped by it. This means fewer carriers, stricter roof and inspection requirements, and a real chance of being declined, especially for older roofs and older mobile homes.
In this guide, we break down what Fort Myers coverage costs, how hurricanes change the picture, and how to compare quotes for site-built, mobile, and vacation homes.
Key Takeaways
- Lee County averages $3,576 a year; your premium depends on roof, location, and home type.
- Roof age and inspections drive approval, and Citizens is the fallback.
- Wind is covered subject to a hurricane deductible; flood needs separate coverage.
- Ordinance and law and the 50% rule can raise rebuilding costs.
- Mobile, manufactured, modular and trailer homes are underwritten differently; seasonal and rental use call for different policies.
How Much Does Fort Myers Home Insurance Cost?
Fort Myers home insurance cost averages about $3,576 a year if we look at Florida homeowners insurance rates by county. That figure covers homeowners and condo unit-owner policies with wind coverage, so your own premium may be higher or lower.
However, an average only shows where the county sits. Roof age, replacement cost, wind-mitigation features, deductibles, and distance from the water move your price more than the county line does. Two neighbors on the same street can pay very different amounts, and these five factors explain most of the gap:
- Roof age and shape. Older roofs and some designs raise wind-loss risk. Therefore, get a roof inspection and ask about credits after a replacement.
- Wind mitigation features. Roof straps, deck attachment, and shutters can earn credits, so make sure to order a wind mitigation inspection.
- Dwelling limit. Confirm the estimate is realistic, not inflated or too low, because a higher rebuilding estimate raises the premium.
- Deductibles. A higher hurricane deductible usually lowers the premium, so weigh the savings against your out-of-pocket risk.
- Claims and home systems. Prior claims and aging plumbing or electrical raise risk, so keep repair records and fix items an inspection flags.
With the main Fort Myers home insurance cost drivers covered, here’s what to check depending on your property location:
Can You Even Get Fort Myers Home Insurance Coverage?
Yes, you can usually get Fort Myers home insurance coverage, but approval depends on the home's age and condition. Carriers screen harder in Lee County than before Ian, so a newer roof and clean inspection reports improve your odds more than shopping alone. Every home insurance company in Fort Myers sets its own guidelines, so a home one carrier declines may still fit another's.
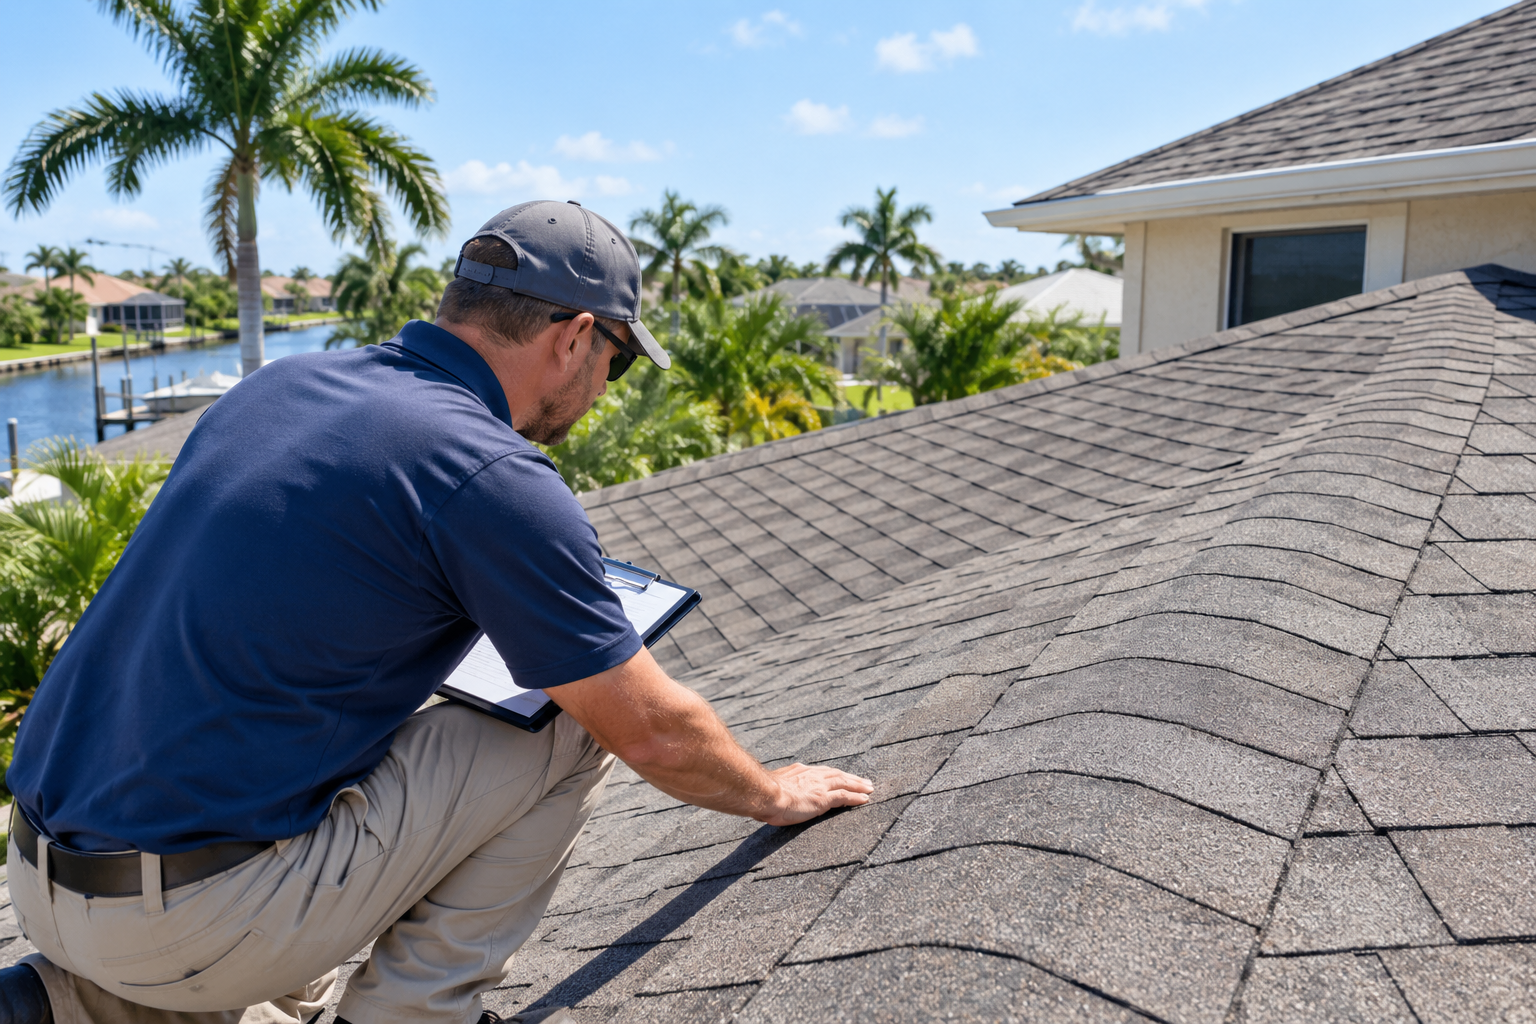
The roof usually comes first. Many carriers set roof-age limits, and an older roof may need repairs, a certification, or a replacement before a carrier will write the policy. Next comes the inspection. The most common insurance home inspection Fort Myers carriers ask for is the 4-point inspection, which checks the roof, electrical, plumbing, and HVAC systems, usually on older homes. A wind mitigation inspection often comes alongside it. It documents the roof shape, roof-deck attachment, roof-to-wall connections, and opening protection, and it can earn premium credits.
Your history and location matter too. Carriers may ask whether storm damage from Ian was fully repaired with permits, and for coastal or river-adjacent homes, flood zone and elevation shape both eligibility and rebuilding rules. Home type is the last piece since mobile homes face tighter age and anchoring requirements than site-built homes.
What If You Get Declined?
If every private carrier declines you, Citizens Property Insurance Corporation is Florida home insurance of last resort. It can cover homes the private market won't, but it comes with trade-offs.
Citizens policyholders can face surcharges and assessments if the company runs a deficit after major storms, so the premium is not always the full cost. Eligibility also depends on whether private carriers offer comparable coverage within a set price range of Citizens' rate, so your agent will need to re-check at renewal. Many owners use Citizens as a bridge while they replace a roof, then return to the private market.
Does Fort Myers Home Insurance Cover Hurricane Damage?
Fort Myers home insurance covers hurricane damage from wind in most standard Florida homeowners policies, subject to a separate hurricane deductible. Flood and storm surge are excluded, so Fort Myers home insurance and hurricanes call for two layers of protection: a homeowners policy for wind and a flood policy for water.
Ian shows why the split matters. NOAA's report on the storm found a peak surge of 10 to 15 feet above ground at Fort Myers Beach, and more than 52,000 structures in Lee County were impacted, 5,369 of them destroyed. Much of the worst damage came from surge, which a standard homeowners policy does not cover.
Wind vs. Water in Practice
- Wind-driven rain. If wind damages the roof and rain enters through the opening, your homeowners policy may respond, subject to the hurricane deductible and policy terms.
- Rising surge. Water that comes in from the Gulf is flood, not wind, and needs a separate flood insurance policy.
- River water. The Caloosahatchee is a flood source too. During Hurricane Ian, the gauge at Fort Myers hit a record water level of 7.26 feet above mean higher high water, so downtown and inland streets are not automatically safe.
New flood policies typically carry a waiting period before they take effect, so buy before a storm enters the Gulf.
Rebuilding After a Storm in Fort Myers
Rebuilding often costs more in Fort Myers than replacing what was there. Three rules explain why:
- Ordinance and law. This coverage helps pay for upgrades current building codes require when you repair or rebuild. Many Florida policies include only a limited amount, so confirm yours.
- The 50% rule. In a flood zone, if repairs reach 50% or more of the building's pre-damage market value, the structure must meet current floodplain rules.
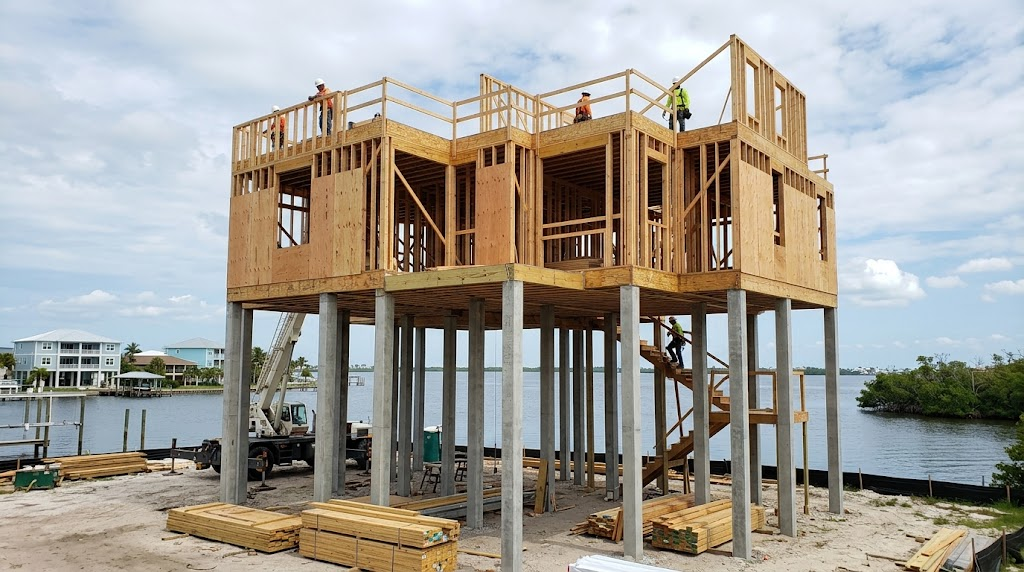
- Elevation. Meeting those rules often means raising the home. NFIP flood policies may include Increased Cost of Compliance coverage of up to $30,000 for qualifying flood losses, which may not cover the full cost.
How the 50% Rule Works
If a structure was worth $200,000 before the damage and repairs are estimated at $120,000, it counts as substantially damaged. In a flood zone, that can trigger the requirement to meet current floodplain standards, which may include elevation.
Now add your policy. For illustration only, if ordinance and law coverage equals 25% of a $300,000 dwelling limit, that is $75,000 toward code upgrades. Actual percentages vary by policy, so check yours. Elevation costs can exceed what ordinance and law and flood coverage provide together, and the gap falls on the owner.
Site-Built, Mobile, Manufactured, Modular, and Trailer Homes in Fort Myers
Carriers sort Fort Myers homes by how they were built, not by what owners call them:
Manufactured home insurance in Fort Myers carriers offer is usually priced on year built, tie-downs, and roof condition, while mobile home insurance for pre-1976 units is the hardest to place. Mobile home insurance quotes can vary sharply, so ask each carrier about age limits first. Trailer home insurance requests are quoted under one of those categories.
On the other hand, modular home insurance quotes tend to look more like site-built pricing, because the home meets local building code on a permanent foundation. Whatever you own, describe how the home was built accurately, since a misclassified home can lead to coverage problems at claim time.
Fort Myers Vacation Home Insurance
Fort Myers vacation home insurance depends on how you use the property. Seasonal (snowbird) use may fit a homeowners or second-home policy, but renting it out usually calls for a landlord policy.
Tell your agent about any rentals. Then consider the Fort Myers-specific risk; an unoccupied home can sit damaged for weeks after a storm, and vacancy provisions can limit coverage for some losses. Report damage promptly, since claim notice deadlines apply.
On Fort Myers Beach and the islands, coverage and flood status also shape what you can rebuild, so confirm flood coverage. Before you leave for the summer, ask your carrier what it expects of an unoccupied home, such as how often someone checks the property.
How to Find the Best Home Insurance Rates in Fort Myers
The best home insurance rates in Fort Myers, FL come from comparing several carriers on identical coverage, not from picking the lowest number. The cheapest quote can carry a high hurricane deductible or thinner roof coverage.
The best Fort Myers home insurance is the policy that fits your roof, flood zone and budget. Home insurance providers in Fort Myers range from Citizens to private carriers such as Slide and Chubb, and availability varies by property.
To lower the insurance premium:
- Claim your wind-mitigation credits with a current inspection.
- Upgrade the roof or openings, such as shutters or impact windows.
- Weigh your deductibles, knowing a higher one shifts cost to you after a loss.
- Bundle policies, such as car insurance, where carriers allow it.
- Verify the dwelling limit reflects realistic rebuilding costs.
Even though none of these guarantees a lower price, the goal is a policy you understand, not just one you can afford this year.
How to Get Fort Myers Home Insurance Quotes
You can get Fort Myers home insurance quotes by gathering your home details, comparing carriers through an independent agency, and reviewing coverage before you buy.
Worth Insurance is an independent agency based in Palm Beach Gardens, serving Floridians since 2018. We compare quotes across multiple carriers instead of selling one company's policy, matching your property to carriers that write it.
Final Thoughts
Fort Myers home insurance is a market shaped by Hurricane Ian, but it is navigable. Know your roof, schedule inspections early, understand your hurricane deductible, and keep wind and flood coverage separate in your thinking. Then compare more than one carrier.
Fort Myers Home Insurance FAQs
#1. What is the average cost of homeowners insurance in Fort Myers, Florida?
The average cost of homeowners insurance in Fort Myers, Florida is about $3,576 a year across Lee County, based on OIR's data. That figure includes wind coverage, and individual premiums vary with roof age, home value, deductibles, and location.
#2. Why did my insurance increase so much after Hurricane Ian?
Insurance rose sharply after Hurricane Ian because insurers faced large losses and higher claims and reinsurance costs across Florida. Premiums have begun easing in many counties, including Lee, but your renewal still depends on your carrier, roof, deductible, and claims history.
#3. Is a modular home insured like a mobile home?
A modular home is generally insured more like a site-built home than a mobile home, because it is built to state and local building code and set on a permanent foundation. Carriers decide case by case, so confirm how yours classifies the home.
#4. What if every private carrier declines me in Fort Myers?
If every private carrier declines you in Fort Myers, Citizens Property Insurance Corporation may be your fallback as Florida's insurer of last resort. Eligibility rules apply, and surcharges are possible, so ask an agent to recheck the private market at each renewal.
#5. Can I get home insurance in Fort Myers with an older roof?
You can sometimes get home insurance in Fort Myers with an older roof, but options narrow as the roof ages. A roof inspection, certification, repairs, or replacement may be required, and some carriers will decline the home or limit roof coverage.

Get a
Florida Home Insurance
Quote
To see how Worth can reduce your risk.
Get a Free Quote


